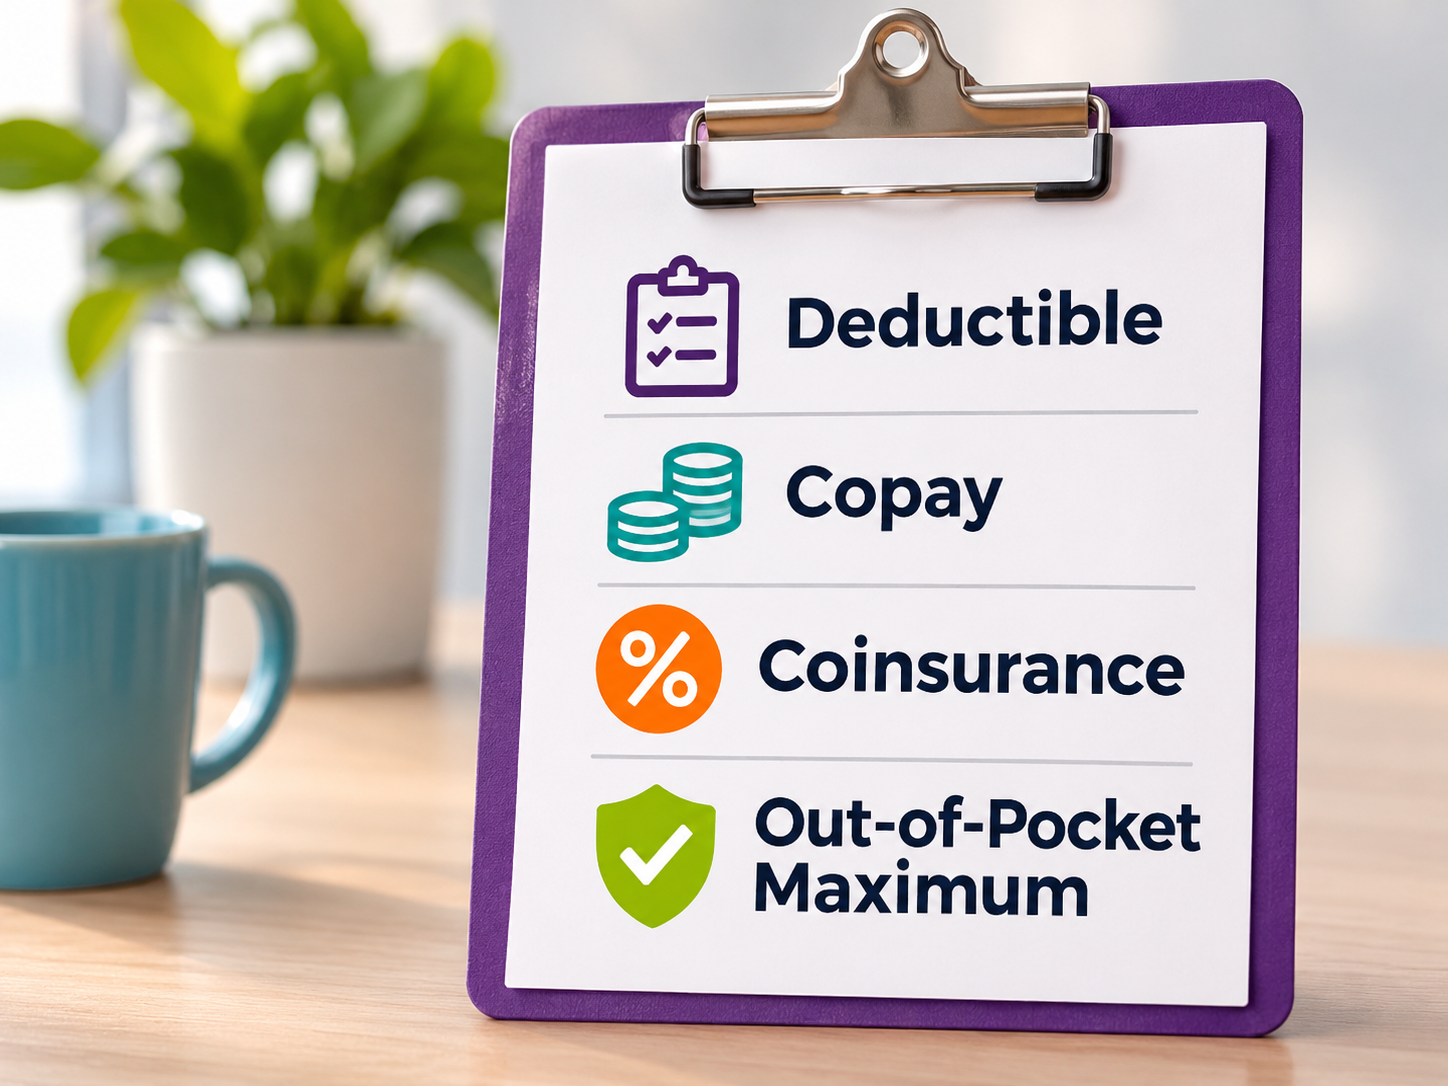
A doctor’s appointment might cost a flat $30, while a test ordered during that visit leaves you paying hundreds. Your insurance can cover both services while applying different payment rules.
The amount you owe depends on the price your insurer and provider have agreed on, how much of your deductible you’ve already met, and the copay or coinsurance for that service. Your out-of-pocket maximum puts a ceiling on your share of covered in-network care.
Start with one employee and an example plan
Alex visits a primary-care doctor for knee pain and is referred for a diagnostic scan. We’ll use an illustrative plan and prices, with employee-only coverage and all care covered and in network.
| Part of the plan | Alex’s coverage |
|---|---|
| Annual deductible | $1,000 |
| Primary-care copay | $30 per visit; deductible waived |
| Coinsurance for the scan | Alex pays 20% after meeting the deductible |
| Annual in-network out-of-pocket maximum | $4,000, including the deductible, copays, and coinsurance |
Earlier in the year, Alex paid $400 for covered care, all of it toward the deductible.
The appointment costs a $30 copay
A copay is a fixed dollar amount for a covered service. Alex pays $30 for the appointment because this plan waives the deductible for primary-care visits. The insurer pays its share of the visit even though Alex still has deductible spending ahead.
Under this example plan, the copay counts toward the out-of-pocket maximum but leaves the deductible unchanged. Alex still has $400 credited toward the deductible and now has $430 toward the annual spending limit.
The doctor orders a scan, which has its own cost-sharing rule: deductible first, then 20% coinsurance.
The scan starts with the insurer’s agreed price
The imaging provider submits a $2,500 charge, but its contract with Alex’s insurer sets the price at $2,000. That agreed price is the allowed amount.
The provider applies a $500 contractual discount, leaving $2,000 to divide between Alex and the insurer. Alex gets that negotiated price even before meeting the deductible.
First, finish the deductible. Then split the remaining cost.
The deductible is the amount Alex pays for services subject to it before the plan starts sharing those costs. Since $400 of the $1,000 deductible is already met, the first $600 of the scan completes it.
That leaves $1,400. Alex’s coinsurance is 20%, so Alex pays $280 of that remaining amount and the insurer pays $1,120.
Alex owes $880 for the scan: $600 toward the deductible plus $280 in coinsurance. The earlier $30 appointment copay was for the doctor’s visit.
The deductible is now met for the year. Another covered scan with the same $2,000 allowed amount would cost Alex $400 in coinsurance, as long as the out-of-pocket maximum hasn’t been reached.
The out-of-pocket maximum caps what Alex pays
Deductible spending, copays, and coinsurance all count toward the out-of-pocket maximum in this example. After the appointment and scan, Alex has $1,310 credited toward the $4,000 limit: the earlier $400, the $30 copay, and the $880 scan bill.
Suppose further treatment brings that total to $3,850 later in the year. Alex now has just $150 left before reaching the maximum. Another covered $2,000 scan would normally mean $400 in coinsurance, but Alex would pay only $150. The insurer would pay the remaining $1,850.
From that point, the plan pays the full allowed cost of covered in-network care for the rest of the applicable year. The $4,000 ceiling includes Alex’s deductible, copays, and coinsurance.
Here’s how the same covered $2,000 scan changes depending on Alex’s spending so far:
| Where Alex stands | Alex pays for the scan |
|---|---|
| $600 of the deductible remains | $880: the remaining deductible plus 20% of the balance |
| Deductible met; at least $400 remains before the spending limit | $400: 20% of the allowed amount |
| Only $150 remains before the spending limit | $150 |
| Out-of-pocket maximum already reached | $0 |
What sits outside that spending limit?
Your monthly premium, including the portion deducted from your paycheck, is separate from these care costs and continues after you reach the maximum. Noncovered services and charges above the allowed amount also sit outside the limit. Out-of-network benefits can have separate deductibles and spending limits, or no annual limit.
When reading your own plan, check whether medical and prescription costs share a limit or have separate limits, and look at both individual and family amounts. Also check the annual reset date in the plan documents.
Match the provider’s bill to the explanation of benefits
After processing the claim, the insurer sends an Explanation of Benefits, or EOB. It shows the provider’s charge, the allowed amount, the insurer’s payment, and your share. The provider sends the bill requesting payment.
For Alex’s first scan, the EOB should show $880 as the patient responsibility. Any payment Alex already made for that scan should reduce the balance on the provider’s bill. Compare the date and service on both documents, then check that the bill reflects the insurer’s calculation and your previous payments.
If the amounts don’t line up, ask the provider’s billing office to explain the balance. Ask the insurer about the deductible, network status, or coverage decision used to process the claim.
Put your own plan’s numbers into the example
Before a planned test or procedure, ask for an estimate based on the negotiated price and check your remaining deductible and out-of-pocket balance in the insurer’s member portal. Confirm which service benefit applies, including whether the deductible is waived.
Washington employers can use the same walkthrough during enrollment or a benefits orientation. Your broker and BHT can work through the plan highlights and Summary of Benefits and Coverage for your group’s options, showing employees what they’d pay for an appointment, a test, and care later in an expensive year.
Related Posts
Bronze, Silver, Gold, and Platinum are federally defined categories that describe how a health plan shares covered costs … Bronze, Silver, Gold, and Platinum: What Do the Metal Levels Mean?
Titanium, Sterling, and Cobalt are three Premera plan families available through Business Health Trust. The main differences are … Titanium, Sterling, and Cobalt: What do Premera plan families mean?
A traditional POS plan is closest to an HMO with an added benefit for care outside the network. … Is a POS Plan More Like an HMO or PPO?
An EPO is usually more like an HMO in where you can get covered care, and more like … Is an EPO More Like an HMO or PPO?
Kaiser’s plan name can change whether an employee can keep an outside doctor, where they can have surgery, … Kaiser Through BHT: HMO, Virtual Plus, PPO, and KP Plus Explained
The lights go out. You find the flashlight. Then the harder questions start: How will you charge your … The Power’s Out. Now What?